

The Japanese economy is shifting from a period of deflation to one of inflation. When considering the relationship between inflation and fiscal policy, one mechanism that is often overlooked is that price hikes provide the government with temporary fiscal space in its budget.
When nominal income, corporate profits, and consumption increase, nominal revenues from income, corporate, and consumption taxes rise elastically. However, public expenditures such as pensions, health care and long-term care, and public-sector salaries are adjusted through changes to institutional rules or the budget process, lagging behind price changes. In this way, inflation creates temporary fiscal space for the government.
It should be noted that this fiscal space merely represents a reduction in the real value of cash, deposits, and benefits, with part of that wealth effectively transferred to the government sector. Such fiscal space is transitional and cannot become a permanent source of revenue.
In democratic decision-making processes, however, there is a strong incentive for the government to use this surplus fiscal capacity for redistribution rather than for fiscal consolidation. This is because while cash transfers and tax cuts serve as direct benefits to voters, fiscal consolidation provides benefits that are broadly dispersed but delayed into the future and are unlikely to generate political gains for politicians.
Even if it is desirable to use this temporary fiscal space generated by inflation for fiscal consolidation, the actual emergence of such surplus capacity may increase the political incentive to prioritize the redistribution of the surplus rather than fiscal consolidation. This can be seen as a political “time-inconsistency problem” where an eventual policy chosen for implementation fails to be consistent with what was viewed as desirable earlier.
Under a structural dilemma characterized by time inconsistency, fiscal policy conducted by politicians and the Bank of Japan’s monetary policy mutually influence one another. Let us frame this relationship as a non-cooperative game between the political authority (government) and the central bank (BOJ).
◆◆◆
The government must choose whether to use its fiscal space for “fiscal consolidation” or “redistribution.” The BOJ also must choose between the “implementation” and “postponement” of “monetary policy normalization.”
In the following figure, preference rankings ranging from 4 for the most preferred to 1 for the least preferred are assigned to the four strategic policy choice combinations A to D.
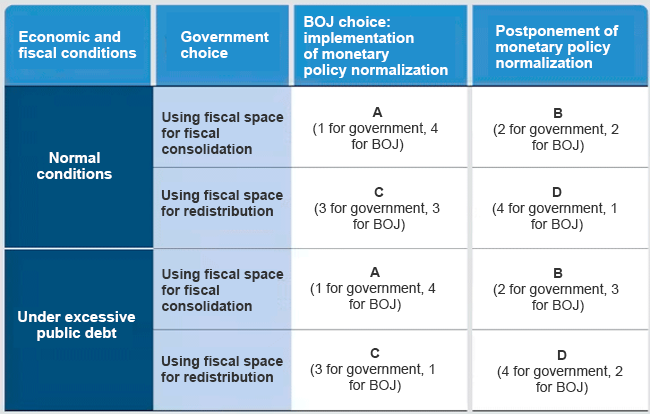
Under normal economic and fiscal conditions, as shown in the upper part of the table, the government’s policy preference order is DCBA. D is the most preferred outcome, allowing the government to avoid the side effect of interest rate hikes while gaining political benefits through redistribution. Conversely, A is the least preferred outcome, leading the government to face downside pressure on the economy through monetary policy normalization without gaining political benefits through redistribution. Redistribution therefore functions as the government’s dominant strategy as it always yields a higher payoff than fiscal consolidation regardless of the BOJ’s strategy.
On the other hand, the BOJ's preference order under normal conditions is assumed to be ACBD. A is the most preferred outcome, allowing the BOJ to achieve price stability while the government maintains fiscal discipline. C is the second-most preferred outcome, leading the BOJ to suppress inflation through monetary policy normalization even if the government chooses to implement redistribution.
Given that the government is assumed to choose its dominant strategy of redistribution, the BOJ compares outcomes C and D and chooses C, monetary policy normalization, as its best response.
Therefore, under normal conditions, the Nash equilibrium is outcome C, which combines redistribution with monetary policy normalization. In this equilibrium, the government stimulates demand through measures aimed at countering rising prices, while the BOJ raises interest rates to offset the inflationary pressure of the stimulus. The result is an “equilibrium of policy conflict.”
However, when the government sector’s accumulated debt exceeds a certain level, the BOJ’s payoff structure changes. If the government fails to control medium- to long-term expenditures, the central bank’s ability to manage interest rates may be constrained, effectively becoming almost subordinate to fiscal policy despite its legally guaranteed independence.
Under conditions of excessive public debt, the costs of monetary policy normalization in outcome C, the Nash equilibrium under normal conditions, increase significantly. Interest rate hikes increase the government’s interest payments through the refinancing of government bonds, while declines in bond prices damage financial institutions’ balance sheets. If tax revenue decreases due to slowing economic activity, the fiscal balance deteriorates again. If stress on the government bond market exceeds an acceptable limit, it cannot be ruled out that the BOJ would be forced to suspend the monetary policy normalization process and expand liquidity provision or government bond purchases.
Time inconsistency occurs here too. Even if the BOJ initially indicates to the market that it would continue monetary policy normalization to pursue price stability, once the burdens on fiscal and financial systems become reality through interest rate hikes, the BOJ may be incentivized to pause monetary policy normalization. If markets anticipate this policy response, the BOJ’s commitment to monetary tightening may lack sufficient credibility, and initial interest rate hikes alone may fail to sufficiently curb inflation expectations or currency depreciation.
At this point, please return to the table’s lower panel “Under excessive public debt.” While the policy preference order for the government remains unchanged, the BOJ’s preference order for C and D is reversed. This is because systemic risks to the financial system and government bond market caused by monetary policy normalization in outcome C exceed the cost of tolerating inflation in D.
Under conditions of excessive public debt, the equilibrium of the game shifts from outcome C to D, combining redistribution with delayed normalization. The government rationally uses its fiscal space for redistribution, while the BOJ changes its best response to avoid shocks to fiscal and financial systems. This is a key mechanism of fiscal dominance. Even without direct government intervention in the BOJ, price stability may consequently become a lower priority.
◆◆◆
Furthermore, it should be noted that this payoff matrix represents not a one-time game but a reduced-form representation of a dynamic game in which budget formulation and monetary policy decisions are repeated.
Market participants act not only by responding to current policies but also by anticipating future policy reaction functions. If it is predicted that the government will repeatedly use temporary fiscal space for redistribution whenever tax revenues exceed expectations, with the BOJ delaying normalization out of concern for the government bond market, future inflation risk premiums will be priced into the Japanese currency.
A weaker currency raises import prices, creating pressure for further fiscal support. Thus, D need not remain a combination of policies at a single point in time; it may develop, through market expectations, into a self-reinforcing “inflation-redistribution equilibrium.”
If this equilibrium persists long enough to allow pensions, wages, and interest payments to fully catch up with price levels, the initial fiscal space will disappear. However, once permanent benefits or tax cuts are introduced, they are difficult to reverse, and the underlying fiscal conditions will deteriorate gradually.
To avoid such deterioration, the government first should eliminate the fiscal illusion of viewing higher-than-expected tax revenues as a permanent source of funding. A rule should be established whereby temporary tax revenue increases associated with inflation are in principle to be used for debt reduction and fiscal consolidation. Second, the government should limit measures to address rising prices to targeted transfers and be cautious about broad-based subsidies and permanent tax cuts that distort market price mechanisms.
Achieving stable nominal growth is important. There is also scope to use mild inflation consistent with price stability to advance fiscal consolidation. However, any temporary fiscal space generated during this process should not be regarded as a permanent source of funding for redistribution. It is essential for political leadership to establish a sustainable fiscal structure that can stand on its own, without relying on indirect central bank support.
>> Original text in Japanese
* Translated by RIETI.
September 11, 2026 Nihon Keizai Shimbun
